· Hankyu Kim · Estimation · 3 min read
Ito Calculus and Ito's Lemma
Understanding Brownian motion, Wiener processes, and why Ito calculus is necessary for stochastic systems.

Brownian Motion and Wiener Process
Brownian Motion describes the random movement of particles caused by collisions with surrounding molecules.
A Wiener Process is a mathematical model of Brownian motion.
A standard Wiener Process satisfies
Therefore,
The expected value remains zero, while the variance increases with time.
For a time interval , the Wiener increment follows
Wiener increments over non-overlapping time intervals are independent.
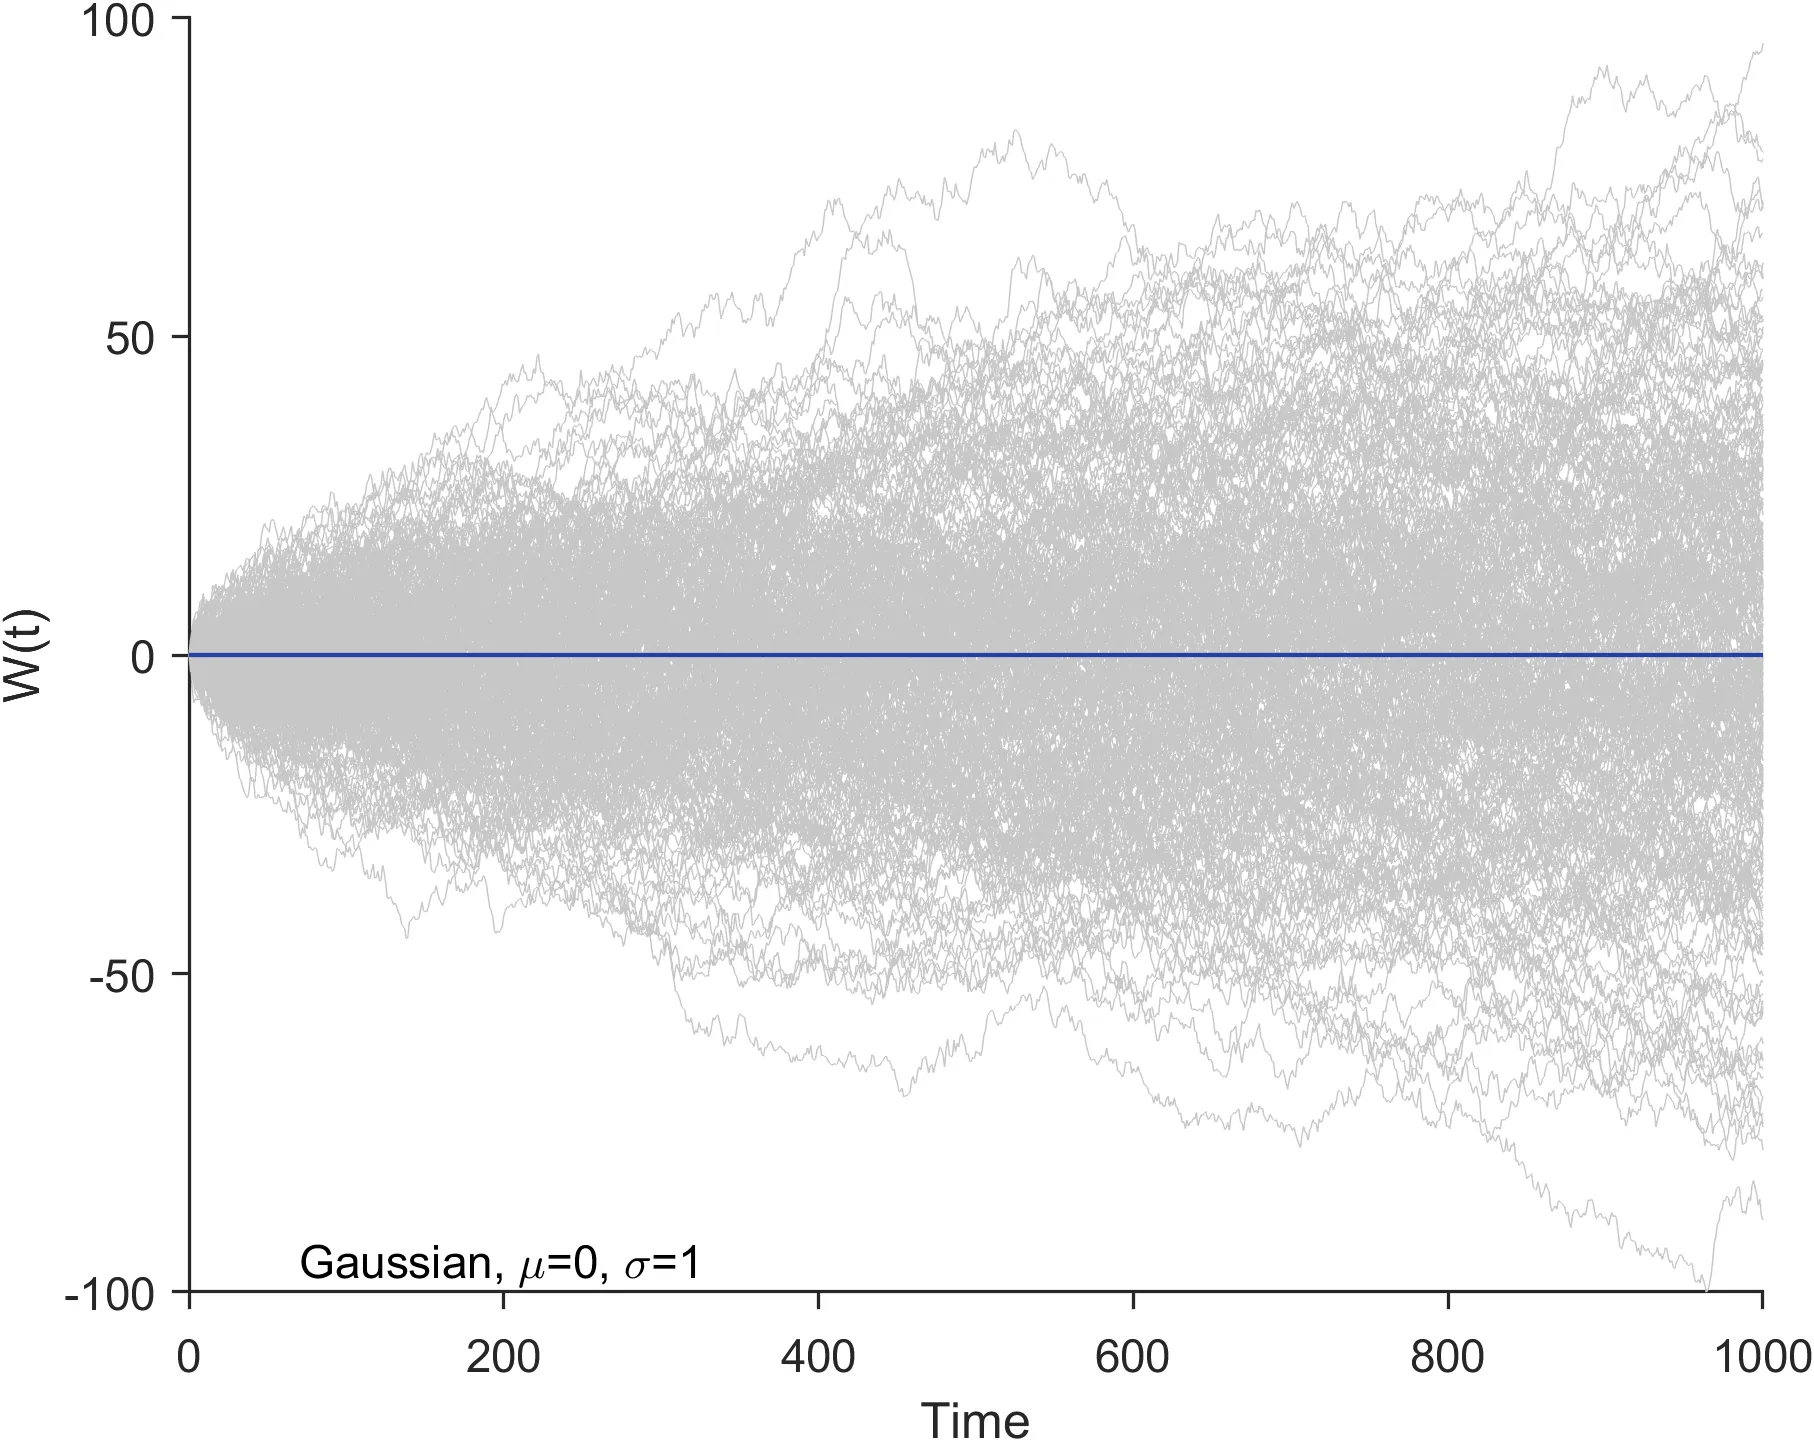
In MATLAB, a Wiener increment can be generated using
dw = sqrt(dt) * randn;Starting with a Simple Position and Velocity Model
Suppose a vehicle moves with constant velocity.
Integrating,
However, actual velocity may contain random fluctuations.
where represents Gaussian white noise.
Ideal Gaussian white noise cannot be integrated using conventional calculus because it is not an ordinary function.
Instead, we model its accumulated effect using Wiener increments.
Formally,
The system becomes
where:
- : deterministic change
- : stochastic change
This is a Stochastic Differential Equation (SDE).
Why Is Important?
In conventional calculus, higher-order infinitesimal terms such as are neglected.
However, Wiener increments behave differently.
Since
we have
This leads to the fundamental Itô calculus rule:
This is a symbolic rule based on the quadratic variation of Wiener processes, not an exact equality for individual increments.
The Itô multiplication rules are
Unlike conventional calculus, the second-order Wiener term cannot be ignored.
This produces the additional term in Itô’s Lemma.
What Is Ito Integration?
Consider a stochastic differential equation:
where describes deterministic dynamics and determines the noise intensity.
For example,
Integrating,
The last term is a stochastic integral.
Itô integration defines how to integrate with respect to Wiener increments.
The integrand is evaluated at the beginning of each time interval, and the limit is understood in a stochastic sense.
What Is Ito’s Lemma?
Itô’s Lemma is the Chain Rule for stochastic processes.
Suppose
and define
In conventional calculus,
However, consider the exact change:
Expanding,
Since ,
Using the Itô rule ,
The additional is called the Itô Correction Term.
General Form of Ito’s Lemma
Suppose
and
Then Itô’s Lemma gives
Compared with the ordinary Chain Rule, the additional term is
This is the Itô Correction Term, which arises because .
Itô’s Lemma allows us to calculate how a function of a stochastic state evolves.
Summary
- Brownian Motion: Random particle movement.
- Wiener Process: Mathematical model of Brownian motion.
- Stochastic Differential Equation: Dynamic system with random noise.
- Itô Integration: Integration with respect to Wiener increments.
- Itô’s Lemma: Chain Rule for stochastic processes.
- Itô Correction Term: Additional term caused by the quadratic variation of Wiener processes.
The key relationship is
Wiener processes model random disturbances, Itô integration defines their accumulation, and Itô’s Lemma describes how functions of stochastic states evolve.


